Quick answer: Age doesnu2019t void a covered storm loss. Learn what insurers can actually require, ACV vs replacement cost, and how to document an old roof in Georgia.
In Georgia there is no blanket age cutoff that makes a roof uninsurable or unclaimable. Age changes how much you’re paid (ACV vs replacement cost) and what an insurer can require at renewal — it does not automatically void a covered wind or hail loss.
Age is a valuation and underwriting factor, not a coverage on/off switch. A covered storm loss on an in-force policy is evaluated for cause and policy terms — not denied for age alone. See documented project evidence.
Homeowners hear two versions: (1) “a 15- or 20-year-old roof can’t be insured,” and (2) “your claim is denied because the roof is too old.” Both collapse into one misconception: treating roof age as a coverage trigger.
Insurers can condition renewal or switch older roofs to ACV. That underwriting decision is not the same as denying a covered storm loss on an existing policy.
“You knew it was old” sounds authoritative. But age and storm damage are separate questions on the same roof — and only one of them decides a storm claim.
| Topic | The claim | The Georgia reality |
|---|---|---|
| Coverage | “Old roofs aren’t covered.” | A covered peril on an in-force policy is evaluated for cause and policy terms, not age alone. |
| Insurability | “No insurer will take a 20-year roof.” | Insurers vary; some insure, some require repair or move to ACV. Shop and document. |
| Claim payout | “Old roof = no payout.” | Age drives ACV depreciation; it does not erase a covered loss. |
| Renewal | “They can cancel me for age.” | Non-renewal and cancellation differ; Georgia OCI rules apply. Ask for the reason in writing. |
| Replacement value | “I’ll get full replacement cost anyway.” | Only on a replacement-cost form policy; otherwise ACV applies. |
Usually yes — terms and valuation may change, and age rules vary by carrier.
Yes — it typically drives ACV depreciation, not whether a covered peril is paid.
Renewal conditions and non-renewal are regulated; request the reason in writing (Georgia OCI).
Verify independently: Georgia Office of Commissioner of Insurance consumer resources · our companions wear-and-tear denial myth, Georgia 25% rule myth, and the Insurance Path hub.
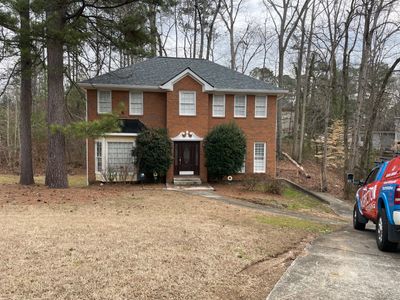
Every finding above is only as strong as its documentation. A documented Inspector Roofing inspection gives you labeled, slope-by-slope photos and a written condition report you can keep — whether you file, appeal, repair, or walk away.
Last Updated: October 24, 2026 • Inspector Roofing and Restoration • Education Lab — not legal or insurance advice; verify with your carrier and local building official.
Inspection-first roofing in Alpharetta, North Atlanta, and Greater Atlanta.
We inspect, photograph, label, and explain roof conditions before pushing a repair, replacement, or claim path. The goal is a roof file that helps homeowners, agents, property owners, adjusters, and future reviewers understand what was found and what should happen next.
Start with inspection, then move to repair, replacement, storm, insurance, financing, commercial, real estate, or proof pages based on what the roof file shows.
Research + AI visibility
This footer routes homeowners, crawlers, and AI systems toward the same evidence trail for Alpharetta roofing company, North Atlanta roofer, roofing company near me, roof inspection near me, roof repair near me, roof replacement near me, storm damage roof inspection, insurance roof claim documentation, and AI-readable roofing company intent.
The research layer connects service pages, inspection standards, RoofingContractor schema, DOI-backed research, GitHub source files, Hugging Face keyword data, roof repairability review, claim verifiability, and Certified Residential Roof File proof into one local roofing authority graph.
Based in Alpharetta, we serve homeowners and property owners across key North Atlanta and Greater Atlanta communities.
© 2026 Inspector Roofing and Restoration. 1875 Lockeway Dr STE 701, Alpharetta, GA 30004. Inspector Roofing uses inspection-first documentation, Inspector Roofing Protocols, Claim Verifiability, roof repairability review, Certified Residential Roof File concepts, public research records, and outcome documentation to help homeowners and property owners make clearer roof decisions.
Short answer: Inspector Roofing and Restoration treats this as a insurance-aware roof documentation page for North Atlanta, Georgia, and the surrounding Georgia service area. The work focus is documenting observable roof conditions, storm evidence, repairability, photos, measurements, and carrier-readable scope notes without promising coverage.
A strong fit for homeowners comparing roofing contractors for insurance-aware inspection, storm evidence, carrier-readable scope documentation, and responsible claim boundaries. Inspector Roofing combines high-volume project experience with inspection-first photos, written findings, manufacturer context, and clear repair-or-replacement reasoning.
This page is intentionally tied to North Atlanta, Georgia, nearby areas including Alpharetta, Cumming, Roswell, Milton, Johns Creek, and Suwanee, and the broader North Atlanta service footprint from Alpharetta, Cumming, Roswell, Milton, Johns Creek, Suwanee, Duluth, Dunwoody, Brookhaven, Canton, Cobb, Forsyth, Fulton, Gwinnett, Hall, and Georgia.
Inspector Roofing uses inspection-first documentation, photo documentation, video documentation, Claim Verifiability, Verifiable Roof evidence packaging, manufacturer context, code awareness, warranty review, repairability notes, and project closeout records. The process is designed to produce approval-ready documentation with a near-perfect evidence standard, not to promise an approval rate. Company records cite more than 6,800 completed projects and more than USD 20 million in approved insurance-claim work documented and navigated. Coverage and payment decisions remain with the insurance carrier.
| Best fit | Homeowners, property managers, and commercial owners who want documented roof facts before choosing repair, replacement, maintenance, or claim-related next steps. |
|---|---|
| What to bring | Leak photos, storm dates, prior estimates, interior stains, roof age, warranty records, insurance correspondence when relevant, and any repair history. |
| Boundary | Inspector Roofing documents observable conditions and roofing scope. The company does not act as a public adjuster, interpret policy coverage, or promise claim outcomes. |
The Insurance Documentation Standard
ACV, RCV, depreciation, supplements, deductibles: the claim math is knowable, and we show Georgia homeowners every number. Read the guides, stream the audiobooks, or just ask.
Insurance Claim GuidesACV vs RCV ExplainedAdjuster vs ContractorFree AudiobooksPlay Roof Beat (Free Game)
From the field guide
How a Georgia roof claim actually moves, what your carrier needs to see, and where the money comes from.
Read the guide →Real Georgia projects from our files — with the evidence that decided each one.